Europe’s biggest caravan group just told the market its profit has more than doubled. It sold less to do it.
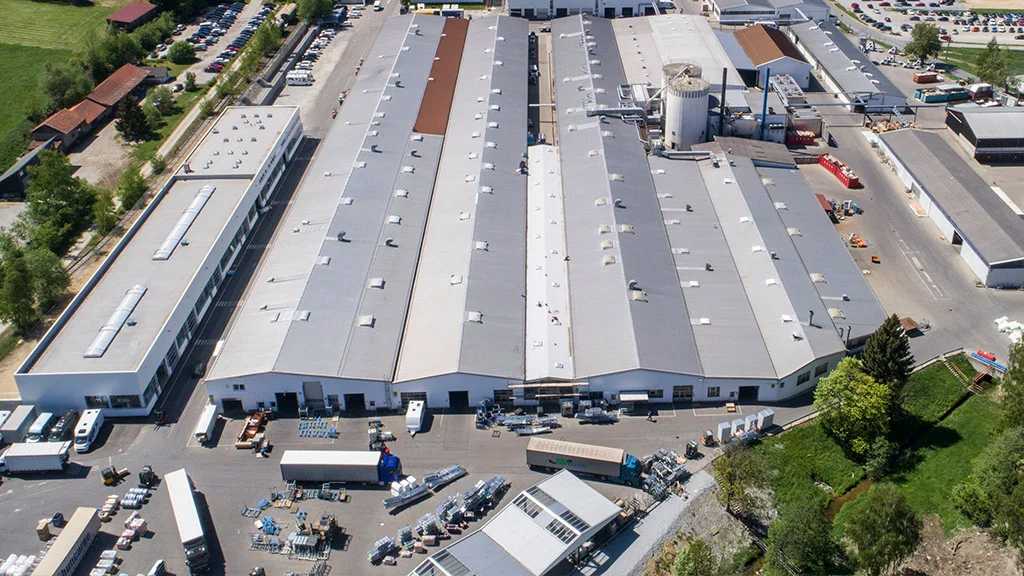
Knaus Tabbert, the German maker behind KNAUS, TABBERT, WEINSBERG, T@B and the MORELO motorhome brand, reported its nine-month 2026 figures on 10 November. Revenue fell to EUR 697.0m from EUR 761.5m. Adjusted profit, measured as EBITDA, rose from EUR 19.8m to EUR 40.5m, up 104.1%. The margin on that profit widened from 2.6% to 5.8%.
A company does not double its profit while its sales drop because buyers came flooding back. They did not. Something changed inside the business, not in the market. That is the part worth a dealer’s time, and so is a quieter line near the bottom of the release that the headline is built to keep you away from.
What the Numbers Actually Say
Revenue is what went out of the factory. EBITDA is a rough read on what the company kept before interest, tax and depreciation. The two moved in opposite directions this year, and the gap between them is the whole story.
Knaus Tabbert is blunt about where the profit came from. The company credits higher total output, a better material cost ratio, and steps to cut its cost base. CFO Radim Sevcik put it plainly, saying the work on the cost structure is showing up in the numbers despite lower revenue.
Read past the CFO quote and it says this: the maker is earning more on each vehicle because its own costs fell, not because it is shifting more metal. The same relief we flagged when Lowdham Leisureworld quadrupled its profit on a 3% rise in sales is now visible at the factory that supplies the trade, not just the forecourt that sells to the public.
The demand side stays soft, and the company says so. It describes subdued demand and cautious ordering from dealers. The order backlog stood at EUR 461m at the end of September. A backlog that size is real work booked, but it sits against revenue that is still falling year on year.
So the picture is a maker running leaner in a market that is not giving it more customers. Good management of a hard year, not a recovery.
The Line the Headline Is Built to Hide
Here is the sentence the press release puts last, under the good news. Knaus Tabbert has financial debt maturing in June 2027, and it has not yet secured a binding deal to refinance all of it. The company says this remains a high priority.
Translate that. A chunk of borrowing falls due in about eighteen months, and the arrangement to replace it is not signed. The maker is being open about it, which is to its credit, but openness does not make the risk smaller.
This matters to a dealer in a way the EBITDA figure does not. A profit number tells you how last quarter went. A refinancing that is still open tells you something about the stability of a supplier you depend on for stock, warranty backing and parts over the next two years.
Be fair about the odds. A profitable group with a healthy order book and a clear plan usually refinances. Lenders prefer a borrower that has just doubled its profit to one that has not. The most likely outcome is a deal gets done and this line disappears from next year’s release.
But “most likely” is not “signed”. If you carry KNAUS, WEINSBERG or TABBERT, this is the single fact in the release worth tracking, far more than the margin.
Why a German Maker’s Figures Reach Your Forecourt
Knaus Tabbert’s home market is the problem behind these numbers. German leisure vehicle demand has been hesitant, and Germany is the biggest market in Europe. When the largest market stalls, a maker that sells across the Continent feels it first.
The UK is not spared that weather. Domestic caravan registrations fell around 7% in 2025, and the touring caravan segment slid across Europe while motorhomes held up better. Knaus Tabbert sells all of these here through UK dealers, so a leaner, more disciplined version of the maker is now the one standing behind your stock.
That cuts two ways for a dealer. A supplier that has fixed its cost base and lifted its margin is a steadier partner than one bleeding money on every van. But a maker focused on protecting margin in a soft market is also a maker less likely to fund deep dealer discounts or carry loose stock. The days of leaning on the factory to move slow metal are thinning out.
This is the same signal we have read off KABE growing its UK Coachman business while British caravan demand falls and off Swift standing up a second motorhome brand to win share in a flat market. The makers that are winning are the disciplined ones. Knaus Tabbert has just posted the clearest version of that yet.
What This Means for UK Dealers
A maker’s balance sheet rarely lands on your forecourt this directly. This one does, and it leaves you three jobs before your next stock order goes in.
Ask your Knaus Tabbert area manager about the June 2027 refinancing. You are entitled to know how your supplier plans to handle debt that matters to your stock and your customers’ warranties. A straight answer tells you a lot. A vague one tells you more. Put the question before your next stock order, not after.
Do not read “profit doubled” as “market recovering”. Revenue fell. The profit came from cost cuts at the factory, not from buyers returning. If you are setting next year’s stock levels off a trade headline about a maker’s profit, you are reading the wrong number. Pull your own registrations and enquiries by brand and judge the year on those.
Expect less room to lean on the factory for discounts. A maker rebuilding its margin will guard it. Price your used stock and your deals on the assumption that manufacturer support tightens, not loosens. Before you fold on a margin to win a sale, check what the deal actually leaves you once you cannot count on the factory to backfill it.
What It Means for Buyers
For a buyer looking at a KNAUS, WEINSBERG or TABBERT, the practical picture is sound. These are established brands with a UK dealer and parts network, built by a maker that has just shown it can run profitably through a downturn. Build quality and support are not in question here.
The honest caveat sits at company level, not product level. A new van comes with a warranty that runs for years, so the maker’s financial footing is a fair thing to weigh. The refinancing is the open question, and the answer is time, not a brochure line. A dealer who knows the plan can reassure a buyer who asks.
The Signal for Next Year
Knaus Tabbert’s results are a read on the trade as much as on the company. The money came back through discipline and cost control, in a market that gave it no extra customers and a home market that is still flat. That is the shape of a good year in this cycle: earned on the cost line, not handed over by demand.
The refinancing is the reminder that even a maker doing the right things is not clear of the weather. A flat market squeezes the balance sheet as well as the showroom, and the biggest names are not exempt.
So here is the question for your forecourt. When the maker behind your best-selling caravans doubles its profit by cutting costs and still has a debt it has not yet refinanced, are you watching the headline it wants you to read, or the line it buried underneath?